Get in touch
Sources last verified: 21 October 2026
Official sources cited at the end of this page.
Has Japan adopted CRS 2.0? Yes. The FY2024 tax reform (令和6年度税制改正) amended the Act on Special Provisions of the Income Tax Act, the Corporation Tax Act and the Local Tax Act Incidental to Enforcement of Tax Treaties (実特法) to carry the OECD’s amendments, and the National Tax Agency (国税庁) says the revised system applies from 2026, with reporting and exchange under it from 2027. Our CRS 2.0 guide for financial institutions sets out the standard itself.
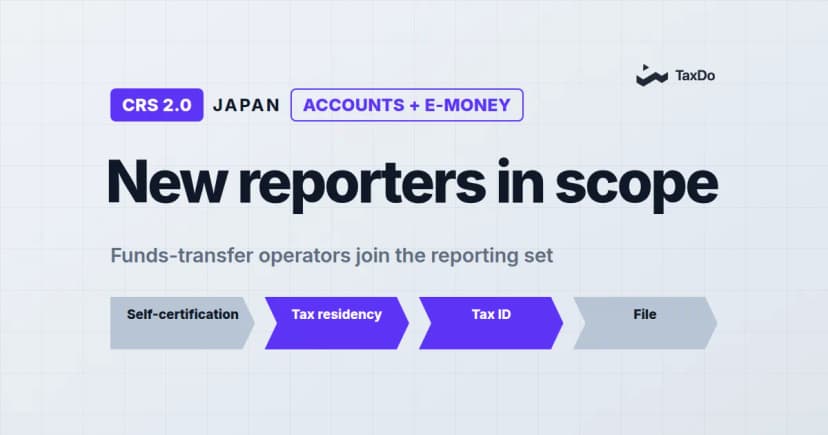
The change reaches products that were outside the regime when Japan began exchanging in 2018: from 1 January 2026, contracts to manage Class 1 to 3 electronic payment instruments under the Payment Services Act and existing digital money come into the reporting regime, and the report adds whether each holder gave a qualifying self-certification form, the account type and whether the account is new or pre-existing.
The failure point is the form at the counter. Since 2017 a customer has had to hand the institution a self-certification form (届出書) when the transaction is made, and the institution must confirm what it says; from 2027 the report itself shows which holders did.
There are two ways to meet Japan’s amended rules. The first collects forms at the counter, then chases and remediates before 30 April. The second completes and tests the self-certification while the customer is still onboarding, so the report is built from data that was clean on Day 1. One finds the gap in April; the other closes it the day the account opens.
01 · Japan CRS 2.0 at a Glance
| Point | Position as at 21 October 2026 |
| Report | By 30 April each year to the head of the tax office for the institution’s head office, by e-filing or recorded media (Art. 10-6) |
| Legal basis | Act No. 46 of 1969 (実特法), Arts. 10-5 to 10-8 and 13, as amended by the FY2024 tax reform |
| Amended rules apply from | 2026; reporting and exchange under them from 2027 (NTA) |
| Self-certification | Form submitted at the transaction, and confirmed by the institution (Art. 10-5(1)); change notice within 3 months, for entities by the later of 31 December and 3 months (Art. 10-5(4); Cabinet Order Art. 6-4(3)) |
| Pre-existing accounts | Contracts held on 31 December 2025 that needed no form and were not already identified: by 31 December 2027 (Art. 10-5(2)(i)); individuals’ contracts over ¥100 million by 31 December 2026 (Cabinet Order Art. 6-3(22)(i)) |
| Records | Five years from the year after the contract ends or another set date (Art. 10-8(2)) |
| Penalties | Up to 6 months’ imprisonment or a ¥500,000 fine for the person who misses or falsifies the report (Art. 13(4)(iv)) and for a customer resident abroad who omits or falsifies the form (Art. 13(4)(iii)); the institution is fined (Art. 13(5)) |
| Exchange | Japan signed the Addendum to the CRS multilateral agreement on 26 November 2024 |
| Authority | National Tax Agency (国税庁, NTA) |
Our regulatory compliance engine readies Japanese banks, securities firms and insurers for the amended CRS from Day 1. It gathers each self-certification form at the transaction, validates the TIN, runs the reasonableness and indicia checks, resolves indicia automatically instead of by your team, and prepares the validated CRS report, with zero remediation, as section 09 shows.
02 · Introduction to Japan’s CRS Obligations
The CRS is the OECD’s model for exchanging financial account information, and the OECD lists 131 jurisdictions committed to it as at 30 September 2026. Its 2023 update was published with the Crypto-Asset Reporting Framework in a single publication of 8 June 2023. Japan has required the self-certification form since 1 January 2017 and its institutions have reported by 30 April each year since 2018 (NTA CRS corner).
The rules sit in Articles 10-5 to 10-8 of the Act on Special Provisions (Act No. 46 of 1969), with the details in cabinet and ministerial orders. Article 10-7 adds an anti-avoidance rule: an act whose main purposes include avoiding the report, or changing what is reported, is disregarded.
03 · Scope of Reporting Financial Institutions
| If you are | Under the amended rules |
| A bank | A reporting financial institution (報告金融機関等) for deposit accounts. |
| A bank, funds-transfer provider or electronic payment instruments service provider | In scope from 1 January 2026 where it manages Class 1 to 3 electronic payment instruments or existing digital money for customers (Cabinet Order Arts. 6-7, 6-8). |
| A securities firm | Reports custodial accounts. |
| A life insurer | Reports cash-value insurance and annuity contracts. |
| A trust or investment fund | Reports equity interests, such as trust beneficiary rights. |
| A crypto-asset exchange | Collects forms from 1 January 2026 and reports 2026 crypto-asset transactions by 30 April 2027 under its own regime (Arts. 10-9 to 10-12). |
More on the crypto side in our Japan CARF article.
04 · Reportable Accounts and Information
Article 10-6 requires, for each reportable contract, the holder’s name, address and residence country, the value of the contract’s assets and the income from them. The NTA leaflet of June 2025 lists the items under the amended rules: name, address, residence country, foreign TIN, whether a qualifying form was submitted, account type, new or pre-existing status, balance and annual interest and dividends.
A contract is reportable where the holder’s residence is a reportable jurisdiction, or where the holder is a specified corporation whose controlling person is resident in one (Art. 10-6(2)).
05 · Self-Certification and Preexisting Accounts
New accounts
A person entering into a specified transaction (特定取引) submits a form giving name, address, residence country and the other prescribed items when the transaction is made, and the head of the institution’s office must confirm it (Art. 10-5(1)). Where someone entering a transaction from 1 January 2026 does not submit the form, the institution must identify the residence from its own information within two years of the transaction, or one year for an individual’s contract above ¥100 million; a corporate contract of ¥25 million or less waits until it passes that amount (Art. 10-5(2)(ii); Cabinet Order Art. 6-3(15), (23)).
Pre-existing accounts
For a contract held on 31 December 2025 that needed no form and has not already been identified, in practice mainly the newly added products, the institution identifies the residence from its own records by 31 December 2027 (Art. 10-5(2)(i)); the Cabinet Order sets 31 December 2026 for an individual’s contract above ¥100 million and defers small corporate and dormant contracts (Art. 6-3(15), (16), (22)).
Changes in circumstances
A holder whose residence or other listed details change submits a change notice (異動届出書) within three months of the change, or of learning of it for a controlling person; an entity has until the later of 31 December and three months (Art. 10-5(4); Cabinet Order Art. 6-4(3)). Where the institution obtains information that contradicts the form, it must ask for a change notice or identify the residence itself by the later of 31 December and three months after obtaining it (Art. 10-5(6)).
06 · Specified Corporations and Controlling Persons
A specified corporation (特定法人) broadly corresponds to the CRS’s passive non-financial entity, and its controlling persons (実質的支配者) are covered by its form (Art. 10-5(1)). Every corporate customer gives the form, but listed companies, their group companies, public bodies and active businesses are not specified corporations and disclose no controlling persons (Art. 10-5(8)(iv); Cabinet Order Art. 6-9); only listed companies, their group companies, public bodies and most financial institutions are also excluded from reporting (Art. 10-6(1); Cabinet Order Art. 6-14). From 2027 the report also carries each reportable controlling person’s role, as the amended CRS requires.
07 · Jurisdiction of Residence Determination
Residence comes first from the form and, where none was given, from the address and other information the institution holds (Art. 10-5(2)). The OECD’s amended Commentary on Section IV expects a dual-resident individual documented or re-documented under the amended standard to declare every residence, without relying on a treaty tiebreaker.
08 · Role of Tax Identification Numbers in CRS 2.0
The form gives the TIN for each foreign residence country that issues one, and the OECD’s amended Commentary (Section VII, paragraph 4bis) does not require a format check; a form without a TIN, where the jurisdiction issues TINs to all residents, gives reason to know it is unreliable. For Japan’s own numbers, the OECD’s Japan TIN sheet lists the 12-digit Individual Number (My Number) and the 13-digit Corporate Number, and notes the safeguards that apply to My Number.
TIN Validation Solutions
Our TIN lookup tool checks numbers in real time against official sources in 130+ countries, and format across 210+, before a wrong number reaches the 30 April report.
09 · Ensuring Compliance and Risk Mitigation
Article 13(4) sets up to six months’ imprisonment (拘禁刑) or a fine of up to ¥500,000 for the person who does not provide the report by its deadline or provides a false one (Art. 13(4)(iv)), and for a customer whose residence country is abroad who does not give the form or gives a false form or change notice (Art. 13(4)(iii)). Where a representative, agent or employee commits the offence in connection with the business, the corporation is fined as well (Art. 13(5)). Records are kept for five years from the year after the contract ends (Art. 10-8(2)).
A fictional Osaka funds-transfer provider manages uncapped digital money balances for 18,000 customers on 31 December 2025, none identified before, because the product was outside the regime. It must identify their residence from its records by 31 December 2027, or 31 December 2026 for an individual above ¥100 million, with small corporate and dormant accounts deferred, while every account opened since 1 January 2026 without a form starts its own identification clock.
At year-end, by hand
Many institutions collect forms at the counter and review before April; each gap found later needs the customer again.
At onboarding, from Day 1
TaxDo runs CRS 2.0 due diligence inside onboarding, in five steps.
Step 1 · Collect the self-certification. Guided and jurisdiction-aware, with a digital signature; a passive entity’s controlling persons and roles in the same flow.
Step 2 · Validate the identity. Every TIN checked in real time against official sources in 130+ countries, and the business against registries in 120+.
Step 3 · Run forensic due diligence with Verify+. Our Verify+ forensic engine runs 20+ checks on an individual and 30+ tax-native checks across eight areas on an entity, including official TIN lookup in 130+ countries.
Step 4 · Cure the gaps, without the compliance team:
4a · New accounts. Reasonableness tested and discrepancies resolved in the same session.
4b · Existing accounts. One click starts a remediation campaign for the cohort, with guided questions through a link in your brand and every answer checked by Verify+. Each case closes with a signed self-certification and an audit-ready certificate.
Step 5 · Report, and keep the evidence. Schema-validated CRS data, prepared and validated for your institution to submit to the tax office. Our team can also submit it on your behalf on request, as an additional service.
From Day-1 self-certification to CRS XML reporting, with zero remediation.
Our CRS 2.0 compliance software · Solutions for financial institutions
Where this sits, and what it does not touch
It runs beside your KYC provider and core banking system. The reporting obligation, and the responsibility for what is reported, stays with your institution, including where TaxDo submits the report on its behalf at its request. TaxDo runs the due diligence and prepares and validates the report.
10 · Related Reading
Framework articles: CRS 2.0 compliance for financial institutions · CARF and crypto tax transparency · Self-certification under CRS 2.0, DAC8 and CARF · Japan and CARF · CRS 2.0 in Singapore · CRS 2.0 in India
Product: Regulatory compliance engine · Day 1 onboarding validation · Business registry check · CARF compliance software