Get in touch
Sources last verified: 20 October 2026
Official sources cited at the end of this page.
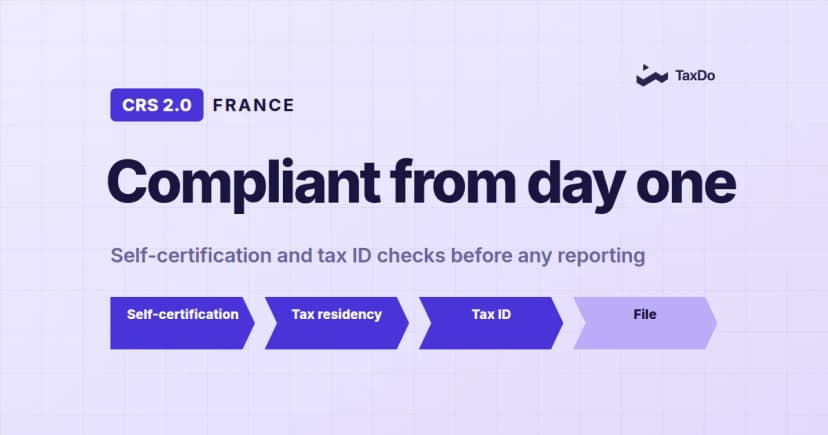
A customer opening an account in Paris leaves the tax-residence box empty. In France the account should not open: an institution that cannot identify a holder’s tax residences, and TINs where required, does not enter into the relationship (Monetary and Financial Code, article L564-1). Since 1 January 2026 that rule covers a wider book, because France applies the OECD’s amended Common Reporting Standard through decree 2025-1277. Our CRS 2.0 guide for financial institutions sets out the framework itself.
The decree, made on 19 December 2025 to transpose DAC8, amends decree 2016-1683, France’s “norme commune de déclaration”. Accounts holding e-money products or central bank digital currencies become depository accounts, and from 1 January 2027 the declaration filed with the tax administration (DGFiP) must also say whether each holder gave a valid self-certification.
The cost of a gap is mechanical. A holder who has not answered a second request within 30 days goes on a list the institution sends to the tax administration (Book of Tax Procedures, article L102 AG), and a declaration filed after its deadline costs EUR 200 for every account to be declared (General Tax Code, article 1736, I, 5).
There are two ways to meet the amended French rules. The first collects forms at onboarding, then chases and remediates before July. The second completes and tests the self-certification while the customer is still onboarding, so the declaration is built from data that was clean on Day 1. One finds the gap in July; the other closes it the day the account opens.
01 · France CRS 2.0 at a Glance
| Point | Position as at 20 October 2026 |
| Self-certification | Obtained at opening and tested for reasonableness against AML records (decree 2016-1683, articles 46 and 53); no relationship where the residences and, where applicable, TINs of the holder and its controlling persons cannot be identified (CMF, article L564-1) |
| Legal basis | General Tax Code (CGI), article 1649 AC; decree 2016-1683 of 5 December 2016, as amended by decree 2025-1277 of 19 December 2025 |
| Amended rules apply from | 1 January 2026; new declaration fields from 1 January 2027 (decree 2025-1277, articles 9 to 11) |
| Authority | Direction générale des finances publiques (DGFiP) |
| Declaration | Before 15 July each year, filed electronically by the institution or a third party it designates (decree 2016-1683, article 54) |
| Records | Data and due diligence evidence kept until the end of the fifth year after the year the declaration is due (CGI, article 1649 AC, I) |
| Fines | EUR 200 per account to be declared for late filing (CGI, article 1736, I, 5); up to EUR 50,000 for breaching the internal control obligation of CMF article L564-2, where neither the ACPR nor the AMF controls that obligation (article 1736, XIV) |
| Crypto-assets | A separate DAC8 declaration by crypto-asset service providers (CGI, article 1649 AC bis), first due before 15 June 2027 |
| Exchange | Within the EU under the directive on administrative cooperation; Addendum to the CRS multilateral agreement signed 26 November 2024 |
Our regulatory compliance engine readies French banks and digital-asset platforms for the amended CRS from Day 1. It gathers each self-certification at opening, validates the TIN, runs the reasonableness and indicia checks, resolves indicia automatically instead of by your team, and prepares the validated CRS declaration, with zero remediation, as section 08 shows.
02 · CRS 2.0 in France: Legal and Market Context
The CRS is the OECD’s model for exchanging financial account information, and the OECD lists 131 jurisdictions committed to it as at 30 September 2026. Its 2023 update was published with the Crypto-Asset Reporting Framework in a consolidated text on 8 June 2023, and the EU carried both into its directive on administrative cooperation through DAC8, Directive (EU) 2023/2226 of 17 October 2023.
France transposed it in two layers. The Finance Law for 2025 (law 2025-127 of 14 February 2025, article 54) created article 1649 AC bis of the CGI for crypto-asset service providers. Two decrees of 19 December 2025, published on 24 December, followed: decree 2025-1276 for the crypto-asset declaration and decree 2025-1277 for the amended CRS. Article 1649 AC itself, in force in its current wording since 1 January 2023, is unchanged: it obliges financial institutions to declare, carry out due diligence and collect the residences and, where applicable, the TINs of holders and of the natural persons controlling them.
03 · Scope and Responsibilities
| If you are | Under decree 2016-1683 as amended |
| A bank | A depository institution; it carries out due diligence and declares before 15 July. |
| An e-money institution | A depository institution from 2026 where it holds e-money products or central bank digital currencies for clients (article 1, III). |
| An asset manager or fund | An investment entity, now including one investing in reportable crypto-assets (article 1, IV). |
| An insurer | Reports cash-value and annuity contracts (article 4, I); capitalisation bonds and contracts are depository accounts (article 4, II, 1°, b). |
| A crypto-asset platform | Declares its users’ transactions under article 1649 AC bis; under the CRS where it holds e-money products or central bank digital currencies for clients, or where holding financial assets for others reaches the 20% gross-income test of a custodial institution (article 1, II). |
Three definitions carry the change. An e-money product is a digital representation of a single legal currency, issued against funds for payment transactions, a claim on the issuer in that currency, accepted by persons other than the issuer and redeemable at par at any time; a product created only to transfer a client’s funds is excluded unless the funds are held for more than 60 days (article 1, VII). A reportable crypto-asset is one that is not a central bank digital currency or an e-money product and can be used for payment or investment (article 1, XI). And a reportable crypto-asset, with any right attached to it, now counts as a financial asset (article 1, V).
Two exclusions limit the reach. An e-money account is not a financial account where its end-of-day balance, taken each day as a 90-day moving average, does not exceed EUR 42,600, the ceiling set by ministerial order (article 9, 3°); so is an account used only to deposit capital for a company’s formation or capital increase, on five conditions (article 9, 2°). A public entity, international organisation or central bank is a non-reporting institution, except for payments on obligations held in a commercial financial activity of the kind a financial institution other than an investment entity carries on and, now, central bank digital currency held for holders that are not financial institutions, public entities, international organisations or central banks (article 3, I, 1°).
04 · Operational Workflow and Compliance Tools
New accounts
For a new individual account, the institution requires a self-certification at opening and confirms its reasonableness against what it obtained when opening the account, including anti-money-laundering documents (article 46). For a new entity account it does the same and, for a passive non-financial entity, identifies the controlling persons; an institution outside the anti-money-laundering regime of article L561-2 of the CMF applies similar procedures to identify them (article 53). The holder must supply the information, including for its controlling natural persons (CGI, article 1649 AC, II).
Pre-existing accounts
An e-money or central bank digital currency account held on 31 December 2025 is a pre-existing account, as is an account opened later that meets four conditions linking it to such an account, among them that opening it requires no new customer information beyond the decree (article 15, I). Where a TIN for a pre-existing account is missing, reasonable efforts to obtain it now also apply whenever the institution updates the account under anti-money-laundering rules (article 22, II).
TIN collection and validation
A holder need not give a TIN where the state of residence issues none or does not require it to be provided (article 57). The OECD’s amended Commentary (Section VII, paragraph 4bis) does not require a format check, but a self-certification without a TIN, where the jurisdiction issues TINs to all residents, gives reason to know it is unreliable. Our TIN lookup tool checks numbers in real time against official sources in 130+ countries, and format across 210+.
Controls and records
Each institution must run an internal control system dedicated to these procedures (CMF, article L564-2), and, for institutions outside ACPR and AMF control, tax agents audit compliance (Book of Tax Procedures, article L80 R). The data and the evidence of due diligence are kept until the end of the fifth year after the year in which the declaration must be filed (CGI, article 1649 AC, I).
05 · Investor and Institution Preparedness
From 1 January 2027, articles 55 and 56 of decree 2016-1683 require the declaration also to state, for every holder, whether a valid self-certification was provided; for a passive non-financial entity, the functions of each controlling person, whose details were already reported; the account type and whether it is pre-existing or new; for a joint account, the number of holders; and, for an equity interest in an investment entity that is a legal arrangement, the functions by which the person holds it (decree 2025-1277, articles 9 and 10).
For an institution, data often held in free text, such as a trust’s controlling-person roles, becomes a declaration field.
06 · France in Global Context
France applies the amended CRS on the same date as the other EU Member States and the United Kingdom, 1 January 2026, while Singapore follows on 1 January 2027. Switzerland also applies the amended CRS from 1 January 2026 but has deferred its crypto-asset rules, and a French group with institutions in Germany or the United Kingdom applies the same amended standard there under each country’s own law.
Crypto-assets held through a platform follow a separate track. A crypto-asset service provider files a DAC8 declaration of its users’ transactions before 15 June of the following year, the first in 2027 for 2026 (decree 2025-1276, article 19), with a fine of EUR 15 per transaction not declared or late, or per inaccuracy, capped at EUR 2 million per provider a year and waived for a first offence in four years that is corrected in time (CGI, article 1736, I, 6). More in France and CARF, the DAC8 guide and our DAC8 compliance software.
07 · Penalties and Controls
| CGI, article 1736 | Amount | For |
| Paragraph I, 5 | EUR 200 per account to be declared | CRS declaration filed late |
| Paragraph XIV | Up to EUR 50,000 | Breach of the internal control obligation of CMF article L564-2, where neither the ACPR nor the AMF controls that obligation |
| I, 6, crypto-assets | EUR 15 per transaction or inaccuracy, up to EUR 2 million per provider a year; first-offence relief | DAC8 crypto-asset declaration late, incomplete or inaccurate |
The late-filing fine scales with the book. A fictional Lyon private bank with 1,200 reportable accounts files its 2026 declaration a week after 15 July 2027: at EUR 200 per account to be declared, the fine is EUR 240,000, whatever the length of the delay.
08 · Two Ways to Meet France’s Amended CRS
At year-end, by hand
Many institutions collect forms at opening and review before July; each gap found later needs the customer again.
At onboarding, from Day 1
TaxDo runs CRS 2.0 due diligence inside onboarding, in five steps.
Step 1 · Collect the self-certification. Guided and jurisdiction-aware, with a digital signature; a passive entity’s controlling persons in the same flow.
Step 2 · Validate the identity. Every TIN checked in real time against official sources in 130+ countries, and the business against registries in 120+.
Step 3 · Run forensic due diligence with Verify+. Our Verify+ forensic engine runs 20+ checks on an individual and 30+ tax-native checks across eight areas on an entity, including official TIN lookup in 130+ countries.
Step 4 · Cure the gaps, without the compliance team:
4a · New accounts. Reasonableness tested and discrepancies resolved in the same session.
4b · Existing accounts. One click starts a remediation campaign for the cohort, with guided questions through a link in your brand and every answer checked by Verify+. Each case closes with a signed self-certification and an audit-ready certificate.
Step 5 · Report, and keep the evidence. Schema-validated CRS data, prepared and validated for your institution to file with the DGFiP. Our team can also submit it on your behalf on request, as an additional service.
From Day-1 self-certification to CRS XML reporting, with zero remediation.
Our CRS 2.0 compliance software · Solutions for financial institutions
Where this sits, and what it does not touch
It runs beside your KYC provider and core banking system. The reporting obligation, and the responsibility for what is reported, stays with your institution, including where TaxDo submits the report on its behalf at its request. TaxDo runs the due diligence and prepares and validates the report.
09 · Timeline
5 December 2016
Decree 2016-1683 sets the French CRS rules under article 1649 AC.
17 October 2023
DAC8 is adopted, carrying the amended CRS and crypto-asset reporting into EU law.
26 November 2024
France signs the Addendum to the CRS multilateral agreement.
14 February 2025
The Finance Law for 2025 creates article 1649 AC bis for crypto-asset service providers.
19 December 2025
Decrees 2025-1276 and 2025-1277 are made, and published on 24 December.
1 January 2026
The amended CRS and the DAC8 crypto-asset rules apply.
1 January 2027
The new declaration fields apply.
2027
The first DAC8 crypto-asset declaration is due before 15 June, and the CRS declaration for 2026 before 15 July.
10 · Related Reading
Framework articles: CRS 2.0 compliance for financial institutions · DAC8 compliance guide · Self-certification under CRS 2.0, DAC8 and CARF · France and CARF · CRS 2.0 in Switzerland
Product: Regulatory compliance engine · Day 1 onboarding validation · Business registry check · CRS 2.0 compliance software