Get in touch
Sources last verified: 20 October 2026
Official sources cited at the end of this page.
30 September 2028 is the date by which The Bahamas expects its first exchanges under the OECD’s amended Common Reporting Standard, according to the Ministry of Finance’s industry briefing of 5 March 2026. The amendments are not yet Bahamian law, and the briefing gives no start date for them. Our CRS 2.0 guide for financial institutions sets out what the amended standard contains.
What changed in 2026 is the enforcement of the current CRS. The Automatic Exchange of Financial Account Information (Amendment) Act, 2026, Act No. 7 of 2026, assented on 23 March, extended portal registration to every financial institution and made failure an offence, required a nil return from a reporting institution with no reportable account, and replaced the compliance-notice and penalty sections, keeping administrative penalties of up to $300,000.
The failure point is the account opened without a self-certification. The Guidance Notes require one before the account opens and, only where that is not feasible, within 90 days; an account still undocumented when the return is built is a gap the Competent Authority can pursue with a compliance notice and a penalty.
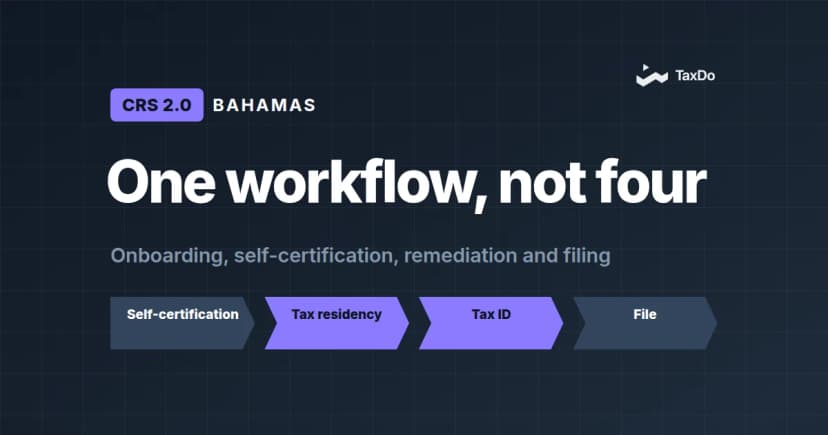
There are two ways to meet the Bahamian rules. The first collects forms at onboarding, then chases and remediates before the filing deadline. The second completes and tests the self-certification while the customer is still onboarding, so the return is built from data that was clean on Day 1. One finds the gap at year-end; the other closes it the day the account opens.
01 · Bahamas CRS at a Glance
| Point | Position as at 20 October 2026 |
| Amended CRS | Not yet in Bahamian law; first exchanges expected by 30 September 2028 (Ministry of Finance, 5 March 2026) |
| Legal basis | Automatic Exchange of Financial Account Information Act, 2016 (No. 37 of 2016) and Regulations, 2017, as amended, most recently by Act No. 7 of 2026 |
| Registration | On the AEOI portal within 90 days of becoming a financial institution; existing unregistered institutions by 15 June 2026 (s. 4, as replaced in 2026) |
| Returns | An information return, or a nil return where no account is reportable (s. 6(1A)), due by 30 June each year (Guidance Notes, Section 2.1) |
| Self-certification | Obtained and validated before the account opens; where not feasible, as soon as practicable and within 90 days (Guidance Notes, Section 5(A)) |
| Penalties | Failure to register: fine up to $100,000 on summary conviction (s. 4(4)); administrative penalty up to $300,000 (s. 15B); six-year limit (s. 15E) |
| Exchange | Returns filed on the portal exchanged by 30 September each year (s. 10(b)); Addendum to the CRS multilateral agreement signed 14 April 2025 |
| Authority | The Competent Authority, Ministry of Finance; the AEOI portal is operated by the Compliance Commission |
Our regulatory compliance engine readies Bahamian banks, trust companies and funds for CRS 2.0 from Day 1. It gathers each self-certification at opening, validates the TIN, runs the reasonableness and indicia checks, resolves indicia automatically instead of by your team, and prepares the validated CRS return, with zero remediation, as section 07 shows.
02 · International Alignment and Strategic Context
The CRS is the OECD’s model for exchanging financial account information, and the OECD lists 131 jurisdictions committed to it as at 30 September 2026. Its 2023 update, published with the Crypto-Asset Reporting Framework in a consolidated text on 8 June 2023, is what The Bahamas has yet to legislate. It signed the Addendum to the CRS multilateral agreement, the instrument for exchanging the expanded data, on 14 April 2025.
Others moved first. The amended CRS has applied in the United Kingdom since 1 January 2026 (SI 2025/740), and DAC8 has applied in the EU since the same date, so a group’s UK and EU institutions within scope already apply the amended rules while its Bahamian ones do not. Our DAC8 compliance software covers the EU side, and our articles on Canada, Argentina and the Cayman Islands cover their timetables.
03 · Scope and Applicability
Today’s rules cover the accounts the original CRS defines: depository and custodial accounts, equity and debt interests in investment entities, and cash-value insurance and annuity contracts held by reportable persons, and controlling persons of passive non-financial entities. A non-reporting financial institution is now defined by reference to Section VIII B of the CRS (s. 2, as amended in 2026).
When the amendments are adopted, the OECD text would bring in accounts holding specified e-money products and central bank digital currencies, derivatives and other interests in relevant crypto-assets as financial assets, and new reporting fields, such as whether each holder gave a valid self-certification and each controlling person’s role. Crypto-assets held through a crypto exchange fall under the CARF instead; the Ministry gives 30 September 2028 for first CARF exchanges too.
| If you are | What to do now |
| A bank or trust company | Register, run due diligence, file the return or a nil return; plan for the amended fields. |
| An investment fund | Register, even if no account is reportable; a nil return is now required. |
| An e-money or digital-asset business | Check whether you are a financial institution today; follow the amendment and the CARF work. |
04 · Customer Due Diligence and Verification
The Updated CRS Guidance Notes of 14 September 2026 set the practice. A self-certification for a new account, opened on or after 1 July 2017, must be obtained and validated before the account opens; where that is not feasible, as on the assignment of an insurance contract, it must be obtained as soon as practicable and within 90 calendar days of opening (Section 5(A)). It includes the TIN for each jurisdiction that issues one and, for an individual, the date of birth, and its reasonableness is checked against the information collected at opening.
The OECD’s amended Commentary (Section VII, paragraph 4bis) does not require a TIN format check, but a self-certification without a TIN, where the jurisdiction issues TINs to all residents, gives reason to know it is unreliable. Our TIN lookup tool checks numbers in real time against official sources in 130+ countries, and format across 210+.
The Act’s anti-avoidance rule (s. 15(1), as substituted by Act No. 18 of 2025) applies to any person, including an intermediary or account holder, who enters into an arrangement or engages in a practice whose main purpose, or one of whose main purposes, can reasonably be considered to be avoiding an obligation under the Act or the Regulations: the Act and Regulations then apply as if it had not happened. That is wider than the Guidance Notes’ summary (Section VIII), which speaks only of a financial institution’s arrangements.
05 · Transaction Capture and XML Reporting
Despite the heading, the CRS does not report transactions. A return reports each reportable account’s balance or value at year-end, or its closure, and the payments in the year: interest for a depository account; interest, dividends, other income and gross proceeds for a custodial account; and the gross amounts paid, including redemptions, for other accounts. Transaction-level crypto-asset reporting is the CARF’s territory, not the CRS’s.
Returns are filed on the AEOI portal, technology approved by the Competent Authority and operated by the Compliance Commission. Under section 10(b) as amended in 2026, information filed on the portal is exchanged by 30 September each year, and a late filing within three months of being filed. The Competent Authority’s notice of 27 May 2026 gives 30 June as the statutory reporting date, kept for the 2025 period, while no administrative penalty applies to reports filed by 31 July 2026. The 31 July date in the Guidance Notes of 21 June 2024 is superseded: the Updated Notes set 30 June from the 2025 period, the concession covered that period only, and Regulation 7 of the 2017 Regulations is still to be amended to match.
Under the wider approach the Guidance Notes adopt, an institution collects and keeps residence information for every account held or controlled by a non-resident, but reports each year only the accounts of persons resident in a Reportable Jurisdiction, one listed in the Second Schedule to the CRS Regulations (Guidance Notes, Sections 2.E and 4.B). The Bahamas’ CRS activation list, as at 12 March 2026, names 73 jurisdictions.
06 · Operational and Compliance Requirements
| Principal Act, as amended in 2026 | Requirement | If missed |
| Section 4 | Register on the AEOI portal within 90 days of becoming a financial institution (excluding portal downtime); existing institutions by 15 June 2026 | Offence: fine up to $100,000 on summary conviction (s. 4(4)) |
| Sections 4A, 4B | Apply to de-register within 90 days of ceasing to be a financial institution (completed only once outstanding returns are filed); notify a change of status within 30 days | Compliance notice and penalty |
| Section 6(1A) | File a nil return where no account is reportable | Compliance notice and penalty |
| Section 13A | Submit to a CRS review by an independent tax expert, at the institution’s expense, where the Competent Authority designates one; the expert reports information that cannot be verified | Compliance notice and penalty |
| Sections 15A, 15B | Remedy a breach within the period in a compliance notice | Administrative penalty up to $300,000 |
No penalty or proceedings may follow more than six years after the breach occurred or ought reasonably to have been discovered (s. 15E), and a penalty does not rule out prosecution, though any fine on conviction is taken into account (s. 15F).
A fictional Nassau fund administrator manages 240 investment funds, 31 of them never registered because none had a reportable account. Under section 4(2) each needed registering by 15 June 2026, and each is now a nil filer under section 6(1A). Every one missed is an offence, with a fine of up to $100,000 on summary conviction, and can attract a compliance notice.
07 · Two Ways to Meet The Bahamas’ CRS
At year-end, by hand
Many institutions collect forms at opening and review before the deadline; each gap found later needs the customer again, and the 90-day window has long closed.
At onboarding, from Day 1
TaxDo runs CRS 2.0 due diligence inside onboarding, in five steps.
Step 1 · Collect the self-certification. Guided and jurisdiction-aware, with a digital signature; a passive entity’s controlling persons and roles in the same flow.
Step 2 · Validate the identity. Every TIN checked in real time against official sources in 130+ countries, and the business against registries in 120+.
Step 3 · Run forensic due diligence with Verify+. Our Verify+ forensic engine runs 20+ checks on an individual and 30+ tax-native checks across eight areas on an entity, including official TIN lookup in 130+ countries.
Step 4 · Cure the gaps, without the compliance team:
4a · New accounts. Reasonableness tested and discrepancies resolved in the same session.
4b · Existing accounts. One click starts a remediation campaign for the cohort, with guided questions through a link in your brand and every answer checked by Verify+. Each case closes with a signed self-certification and an audit-ready certificate.
Step 5 · Report, and keep the evidence. Schema-validated CRS data, prepared and validated for your institution to file on the AEOI portal. Our team can also submit it on your behalf on request, as an additional service.
From Day-1 self-certification to CRS XML reporting, with zero remediation.
Our CRS 2.0 compliance software · Solutions for financial institutions
Where this sits, and what it does not touch
It runs beside your KYC provider and core banking system. The reporting obligation, and the responsibility for what is reported, stays with your institution, including where TaxDo submits the report on its behalf at its request. TaxDo runs the due diligence and prepares and validates the report.
08 · Implementation Timeline
21 June 2024
The Amended Bahamas CRS Guidance Notes are issued.
14 April 2025
The Bahamas signs the Addendum to the CRS multilateral agreement.
July 2025
The Amendment Regulations, 2025 (S.I. No. 80 of 2025) replace the lists of participating and reportable jurisdictions and the Competent Authority’s information powers.
5 March 2026
The Ministry of Finance’s industry briefing gives 30 September 2028 for first exchanges under the amended CRS and the CARF.
23 March 2026
Act No. 7 of 2026 receives assent; it is published on 25 March.
15 June 2026
Deadline for existing financial institutions to register on the AEOI portal.
30 June 2026
Returns for 2025 are due; no administrative penalty applies to those filed by 31 July 2026.
14 September 2026
Updated CRS Guidance Notes are issued: returns due by 30 June each year, and a self-certification validated before the account opens.
Still pending
The amendment adopting the 2023 CRS changes, its start date and the CARF legislation.
09 · Related Reading
Framework articles: CRS 2.0 compliance for financial institutions · CARF and crypto tax transparency · Self-certification under CRS 2.0, DAC8 and CARF · The Bahamas and CARF · CRS 2.0 in Canada
Product: Regulatory compliance engine · Day 1 onboarding validation · Business registry check · CARF compliance software